Florida Hurricane Center
Everything a Florida homeowner needs before, during, and after a storm: what to do, what your policy actually covers, and who to call.
Get your address's Hurricane Risk Score See how exposed your home is, free and instantGet an Email When a Storm Threatens Florida
One plain-English email the moment a storm enters the Florida threat zone: what's coming, and how long before carriers stop writing coverage. No newsletters, no marketing, unsubscribe anytime.
Atlantic Storm Outlook
National Hurricane Center →No active Atlantic storms or areas of development right now. This is the time to prepare: review the checklist below and make sure your coverage is in order, because flood policies carry a 30-day wait.
Data: NOAA National Hurricane Center, refreshed every 30 minutes.
Outlook issued Fri, 11 Sep 2026 11:20:13 GMT.
7-Day Tropical Outlook
Next 7 days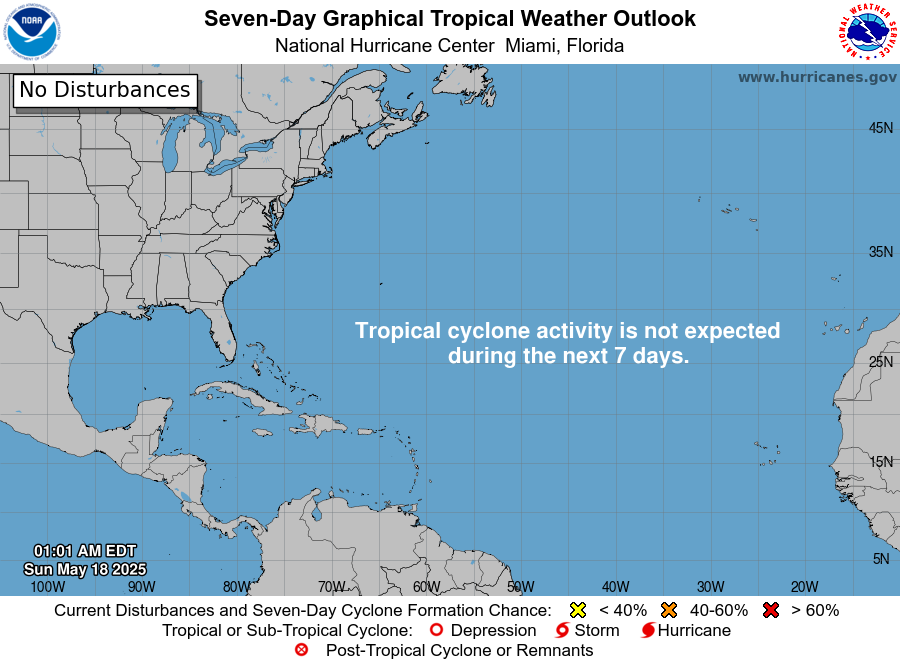
48-Hour Tropical Outlook
Next 2 days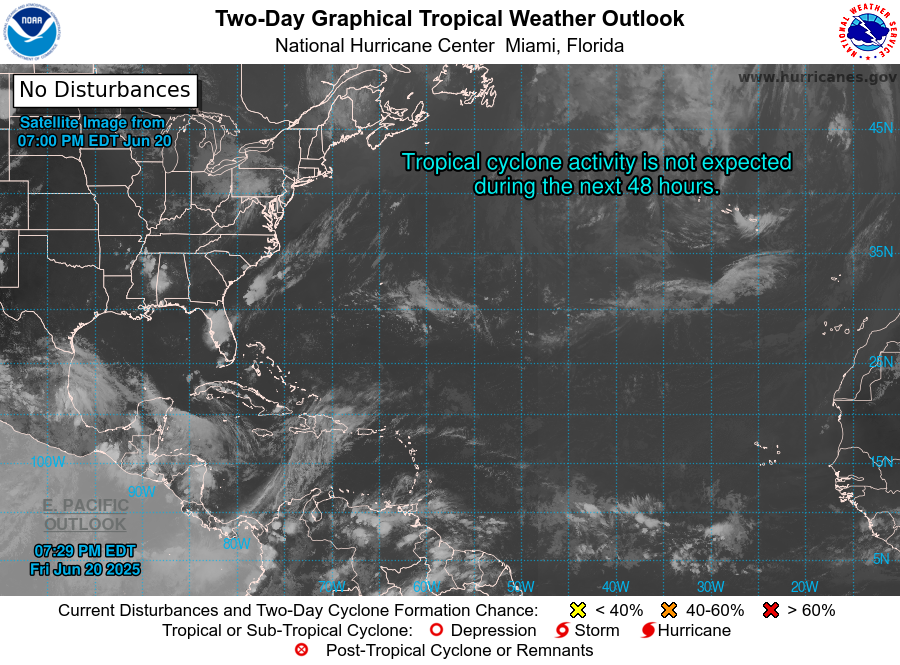
Live graphics from the National Hurricane Center, updated automatically through the day. Shaded areas show where development is possible; click either map for full forecasts and storm tracks.
Hurricane Deductible Calculator
Florida hurricane deductibles are a percentage of your dwelling coverage, not a flat dollar amount. Most homeowners are surprised by the real number.
If a hurricane damages your home, you pay the first
out of pocket before coverage kicks in.
Review My Deductible OptionsWhat Hurricane Categories Actually Mean
The Saffir-Simpson scale measures sustained wind — and each step up is a far bigger jump in damage than the numbers suggest. Here is each category in plain terms, and what it tends to mean for your insurance.
| Category | Winds | Typical damage | The insurance angle |
|---|---|---|---|
| Cat 1 | 74–95 mph | Shingles, gutters, and siding damaged; large branches snap; power out for a few days. | Even a Cat 1 triggers your hurricane deductible — on a $400,000 home with a 2% deductible, the first $8,000 is yours. |
| Cat 2 | 96–110 mph | Major roof and siding damage; shallow-rooted trees uprooted; near-total power loss lasting days to weeks. | Roof age decides claims here: carriers scrutinize older roofs hardest, and depreciation can shrink a payout. |
| Cat 3 | 111–129 mph | Major hurricane. Roof decking and gable ends fail; water and electricity unavailable for days to weeks. | Loss-of-use coverage starts to matter — it pays for hotels and meals while your home is unlivable. |
| Cat 4 | 130–156 mph | Severe roof structure and exterior wall loss; most trees snapped; areas uninhabitable for weeks or months. | The dwelling-limit test: if your Coverage A lags real rebuild costs, this is where the gap shows. |
| Cat 5 | 157+ mph | A high percentage of framed homes destroyed, with total roof failure and wall collapse. | Ordinance & law coverage matters: rebuilds must meet current code, and standard policies cap that upgrade cost. |
Wind ranges and damage descriptions from the NOAA National Hurricane Center Saffir-Simpson scale. Categories measure wind only — storm surge and flooding can be deadly at any category and are covered by flood insurance, not your homeowners policy.
The Insurance-Smart Prep Checklist
Before the Season
- ✓ Walk your home and video everything, room by room, closets and garage included. That video is your claim's best friend.
- ✓ Photograph your roof, or save your last roof inspection or wind mitigation report.
- ✓ Confirm your flood policy. NFIP coverage generally has a 30-day wait, so it cannot be bought when a storm is named.
- ✓ Know your hurricane deductible in dollars, not percent. Use the calculator above.
- ✓ Store policy documents somewhere that survives a power outage: cloud storage or a bag you can grab.
When a Storm Threatens
- ✓Know your evacuation zone and route: check Know Your Zone, Florida's official evacuation zone lookup.
- ✓ Bring in or anchor anything wind can throw: furniture, grills, potted plants.
- ✓ Shutter or board openings; a breached opening is how roofs come off.
- ✓ Charge everything, fill the car, and screenshot your insurance contacts.
- ✓ If told to evacuate, go. Property is insured; people are not replaceable.
After the Storm
- ✓ Photograph all damage before touching anything, wide shots and close-ups.
- ✓ Make only temporary repairs needed to prevent further damage, and keep every receipt.
- ✓ Report your claim fast; carriers work queues in order.
- ✓ Be careful what you sign. Assignment of benefits agreements from door-knocking contractors can sign away control of your claim.
- ✓ Call us. We will help you navigate the claim, that is what we are here for.
What's Your Evacuation Zone?
Evacuation zones are not flood zones — they're the letters (A through F) your county uses to order people out ahead of storm surge, starting with A. Enter your address and know yours before a storm has a name.
Evacuation orders and shelter openings are announced by your county's emergency management office — that's the page to watch when a storm approaches.
Zone from the Florida Division of Emergency Management's statewide Know Your Zone data. Mobile and manufactured homes must evacuate when ordered, in any zone.
What Actually Covers What
The most expensive surprise in Florida insurance is learning this after the storm.
Wind Damage
Covered by: Homeowners policy
Roof damage, broken windows, rain that enters through storm-created openings. Subject to your hurricane deductible.
Storm Surge & Flooding
Covered by: Flood policy only
Rising water is flood damage, full stop, even during a hurricane. While some homeowners policies offer this coverage by endorsement, most do not. Check your flood zone.
Your Car
Covered by: Comprehensive auto coverage
Flooded or wind-damaged vehicles are covered only if your auto policy carries comprehensive coverage, not liability-only.
What Happens After You File a Claim
Florida law puts your insurer on a clock. Knowing the deadlines is the difference between waiting anxiously and knowing exactly when to push.
You report the claim
File directly with your carrier using the contacts above, write down your claim number, then tell us — we follow the claim with you from here.
Carrier acknowledges
Your insurer must review and acknowledge your claim within 7 calendar days of hearing from you. Silence past a week is not normal.
Inspection happens
If a physical inspection is needed, the carrier must conduct it within 30 days of receiving your proof-of-loss statement. Have your photos and receipts ready.
Paid or denied, in writing
The carrier must pay, partially pay, or deny your claim within 60 days of notice — with a written explanation tied to your policy.
These deadlines come from Florida Statute §627.70131 and can pause for factors outside the insurer's control, such as a declared state of emergency after a major landfall. If you haven't heard from your carrier within these deadlines, call us. We're here to help.
Careful What You Sign After a Storm
Florida banned assignment-of-benefits agreements — for policies issued or renewed after January 1, 2023, a contractor can no longer take control of your insurance claim (Florida Statute §627.7152). But door-to-door solicitors still work storm-damaged neighborhoods within hours of landfall, and the contracts they push can still hurt you: direction-to-pay forms, inflated scopes of work, and exclusive repair agreements with steep cancellation fees.
- ✗ Never sign anything on the spot — a legitimate contractor gives you time to read the contract and verify their license.
- ✗ Never let a roofer "handle the claim for you" or waive your deductible — deductible waivers are illegal in Florida.
- ✗ Don't let anyone on the roof before your own photos and your carrier's inspection are done.
- ✓ Send us any contract before you sign it. Reading the fine print costs you nothing — signing the wrong thing can cost you the claim.
Official Florida Storm Resources
The sources we check ourselves. Evacuation orders and shelter openings are county decisions, so start with your own county.
Your County's Emergency Management Office
Evacuation orders, shelter openings, and sandbag sites are decided county by county — bookmark your county's page before you need it. Links open each county's official emergency management site.
Hurricane Insurance FAQs
Wind damage from a hurricane is covered by most Florida homeowners policies, but it is subject to a separate hurricane deductible — typically 2% to 10% of your dwelling coverage rather than a flat dollar amount. What is never covered is flooding, including storm surge and rising water; that requires a separate flood policy. So a hurricane claim can involve two policies, two deductibles, and two adjusters.
Florida policies carry a percentage deductible for hurricane claims. On a home insured for $400,000, a 2% deductible means $8,000 out of pocket; a 5% deductible means $20,000. It applies per hurricane season in Florida, not per storm, once you have met it. Check your declarations page before the season starts — this is the number that surprises people most after a storm.
Usually not. Once the National Hurricane Center names a storm that threatens Florida, most carriers impose binding restrictions — they stop writing new policies, adding coverage, or raising limits until the storm passes. Restrictions can begin days before landfall. If you have a coverage gap, the time to fix it is before a system is named, not when it appears in the forecast.
Yes — storm surge is covered by flood insurance, not by your homeowners policy. This is the single most expensive misunderstanding in Florida. NFIP policies also carry a standard 30-day waiting period before coverage begins, so buying when a storm is already forming does not help. Private flood policies sometimes have shorter waits.
It depends on the damage relative to your hurricane deductible. If repairs are close to or below your deductible, filing may not benefit you and still counts as a claim on your record. Document everything with photos and video first, get a repair estimate, then talk it through with us — as your agent we can help you weigh it before you file, which is something a call center will not do.
Make sure everyone is safe, then document damage thoroughly with photos and video before moving anything. Make reasonable temporary repairs to prevent further damage — tarping a roof, boarding a window — and keep every receipt, since those costs are typically reimbursable. Do not throw damaged property away until it has been documented or an adjuster has seen it. Then file promptly; Florida has deadlines for hurricane claims.
Most homeowners policies include additional living expenses (also called loss of use), which pays for temporary housing, meals above your normal costs, and related expenses while your home is being repaired after a covered loss. Keep all receipts. Note that if the damage was caused by flooding, NFIP flood policies generally do not include this coverage.
Only if you carry comprehensive coverage on your auto policy. Comprehensive covers flood, falling trees, and wind damage to your vehicle — your homeowners and flood policies do not cover cars. If you carry liability only, storm damage to your vehicle is not covered, which is worth reviewing before hurricane season.
Get Storm-Ready With a Free Coverage Review
Tell us how to reach you and a licensed Florida agent will make sure your coverage is ready before the next storm has a name — while carriers are still writing.
